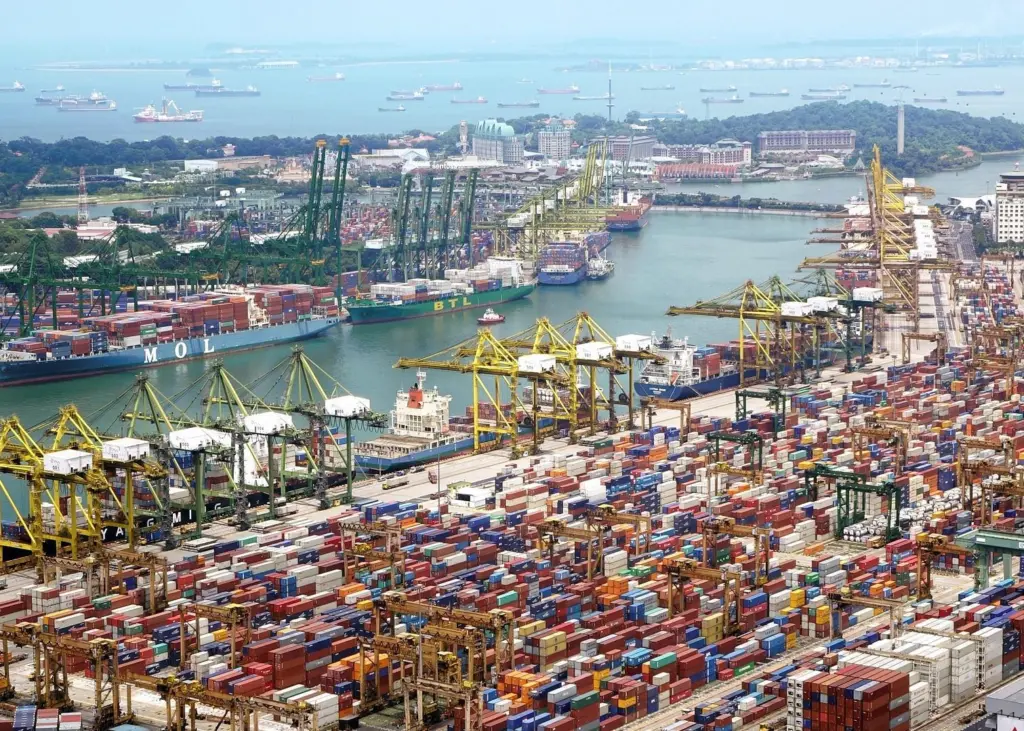
The organisation’s recent Global Port Development Report of Q2 2017 saw port production in the second quarter of this year retain a satisfactory upward trend and maintenance of the global container shipping sector’s recovering trend since Q4 2016.
Container throughput at the major ports studied increased by 7.2% year-on-year, and was up by 9.8% quarter-on-quarter, with the growth rate increasing again in comparison to that of the previous quarter.
The report also noted that while dry bulk throughput at major world ports offered differing trends of growth, liquid bulk throughput at ports studied maintained the previous quarter’s trend of growth.
Major terminal operators included in the report all registered positive throughput growth, with the exception of COSCO Shipping Ports Limited.
Key trends
The Q2 2017 report also identified a number of features of the period concerning global ports.
One was the boom in domestic cargo throughput at Chinese ports, with the rate increasing by 7%, compared with an increase of 1% in Q2 2016.
2017’s second quarter also saw a polarisation of growth rates of cargo throughput at South Korean ports and increases in container throughput at both European and American ports. However, the report identified a slowing of dry bulk cargo throughput growth at Australian ports.
Another feature was the lack of change in the rankings of the world’s top ten ports for cargo throughput. A final trend concerned the varied performance in Q2 by different terminal operators in terms of equity throughput.
COSCO Shipping Ports witnessed negative growth for the first time since its merger, with its equity throughput decreasing by 2.7% year-on-year, while China Merchants Port Holdings Company saw its year-on-year growth improved from the same period from the year before.