Back and forward
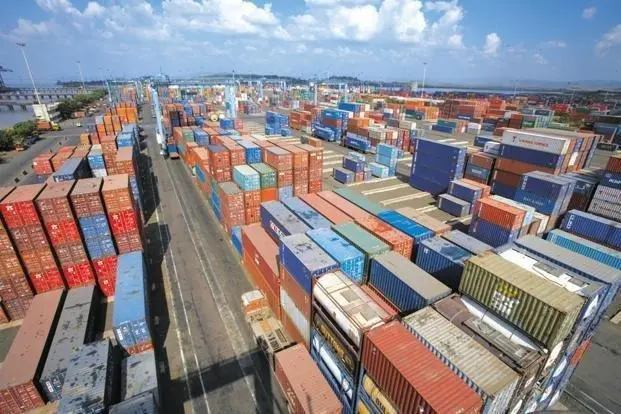
Another year draws to a close leaving inits wake some memorable positives and negatives. The big positive has to be thebusiness climate – we may currently be beginning to feel a slightly tougherenvironment but for the most part, this year has been another one of significantgrowth across all key sectors. Asia-Europe container trade has been a starperformer maintaining strong double-digit growth and who would have thought thatAsia-Middle East container trade would emerge as the worlds fastest growingcontainer trade?
Other major positives for the year have to be the influx of money into the port business and the new players that are in part responsible for this – pension funds, infrastructure funds, private equity interests and so on. This has even led to the remarkable phenomena of one or two shipping line interests “cashing out” at the top of the market rather than the more usual forced course of action of disposing of port assets at the bottom of the market. And whatever did happen to the old cycle of boom and bust in the container sector, we haven’t seen this for a while?
We have also seen various market hotspots consolidate or appear on the scene. Baltic container trade continues to climb on a double digit basis. Black Sea container services continue to expand and spur the requirement for new container handling capacity. The eastern Mediterranean also progressively came of age – Turkey continued to roll out its privatisation programme, Syria established its first private sector container handling operation and Egypt introduced more private sector expertise and laid significant expansion plans. Greece also moved ahead with its preparations to privatise container handling. In Asia, China continues to grow and Vietnam has established its position as a young contender.
There is a lot, looking back on 2007, to be thankful for even if there are one or two big negatives. The PS prize in the latter respect has to go to the US for its hugely blinkered initiative requiring the scanning of all US-bound containers. If ever there is an industry initiative that will rack up costs and suppress efficiency this is it. So step up whoever it is from the US that was in the driving seat with this idea and take the annual PS award for shooting the industry in the foot, you deserve it!
Emerging thinking seems to be that the year ahead may not be so good but is this based on fact or a natural pessimism? There are some worrying signs, you know those two words that we have all become familiar with over the last few months, but which previously we were totally oblivious to: “sub prime”. But do these sort of financially-based problems really signal a serious downturn or an adjustment? The latter is perhaps a more reasonable assumption.
There are also structural problems: will infrastructure development keep up with capacity requirements, and will tightening capacity lead to a sustained hike in costs? Witness the recent hoo ha over the decision of the Far East Freight Conference to impose a congestion charge on westbound cargo from Asia to the UK. It is also clear that a huge number of 10,000teu+ containerships have been ordered and that it will take some significant growth to soak up this capacity.
But are these sort of challenges really any different from what we have confronted before? I don’t think so – isn’t the answer the same as before? We simply have to build on our successes, raise our “game” and most important continue to innovate. This is our agenda!
Have a great Christmas and a prosperous New Year from all of us at PS.
Related Articles
 VIEWPOINT