




Trust and credibility still at stake
One of the key issues to emerge at the 12th Global Liner Shipping conference in London was the continuing mistrust between shippers and carriers.
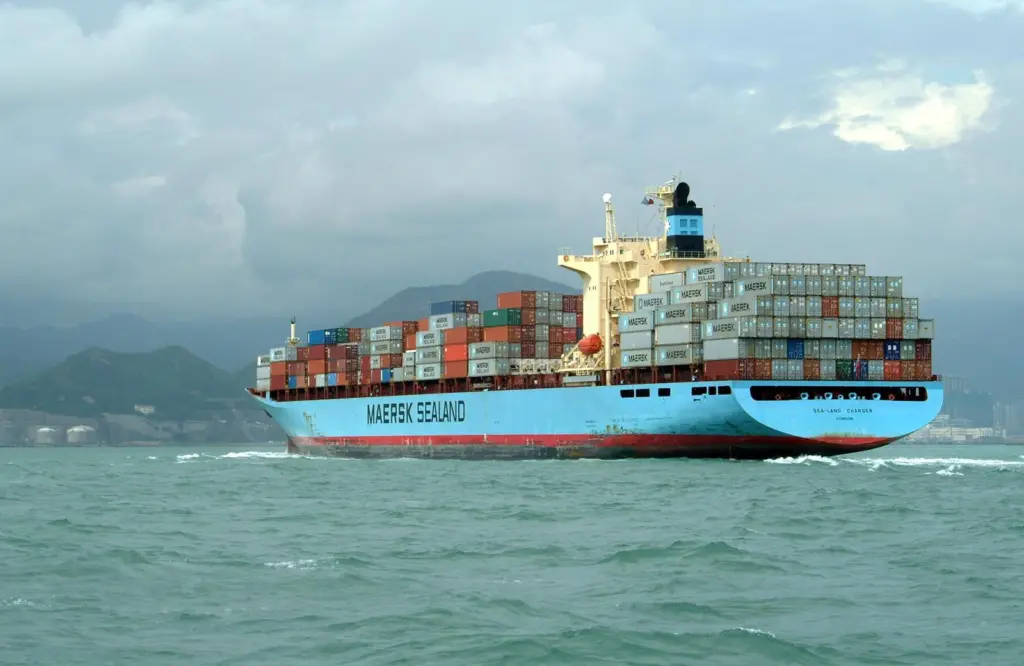
This despite the end of the conference system in Europe which should have dispelled some of the historical animosity between the two sides.
There was a litany of complaints by shippers about the steady stream of surcharges being applied on top of freight rates that have risen so dramatically after their equally dramatic decline in 2009. Shippers also felt badly done by when it came to changes in schedules and sailings, all being done without prior notice or discussion. This is not a new grievance as the acrimonious exchanges at the TPM conference in Oakland, California last month showed.
The response from the carriers has been fairly unanimous: “You wanted an end to the conference system, now you have it, live with it” or words to that effect.
Besides the surcharges, shippers are complaining about lack of capacity to ship their goods and are accusing the carriers of manipulating the market. The response of the carriers to this was that they were on the precipice of total bankruptcy and individually decided that they needed to reduce their costs and adjust capacity to meet demand. In doing this they have managed to bring the freight rates back up dramatically on some trades. Simple economics of supply and demand.
In the North American market shippers are raising similar complaints. Under anti-trust exemption rules, carriers are free to coordinate certain activities such as surcharges and recommended price increases within the framework of discussion agreements. Following these complaints, the FMC is carrying out a study to investigate whether there was a common link between capacity shortages and increasing freight rates in order to assess whether or not there were improper discussions.
Yet even with the elimination of conferences in Europe the industry remains confrontational. It has not yet managed to find a way to be credible about its pricing structure nor have the two sides managed to find a level of trust that might help to reduce the volatility of the cost of shipping. Nothing, then, has changed.
Related Articles
 INSIGHT & OPINION
 INSIGHT & OPINION
 INSIGHT & OPINION