






Drewry: box terminal complexity intensifying
Drewry has released its annual Global Container Terminal Operators report for 2016 which has highlighted the increasing complexity of the industry and the changes caused by mergers and acquisitions (M&A).
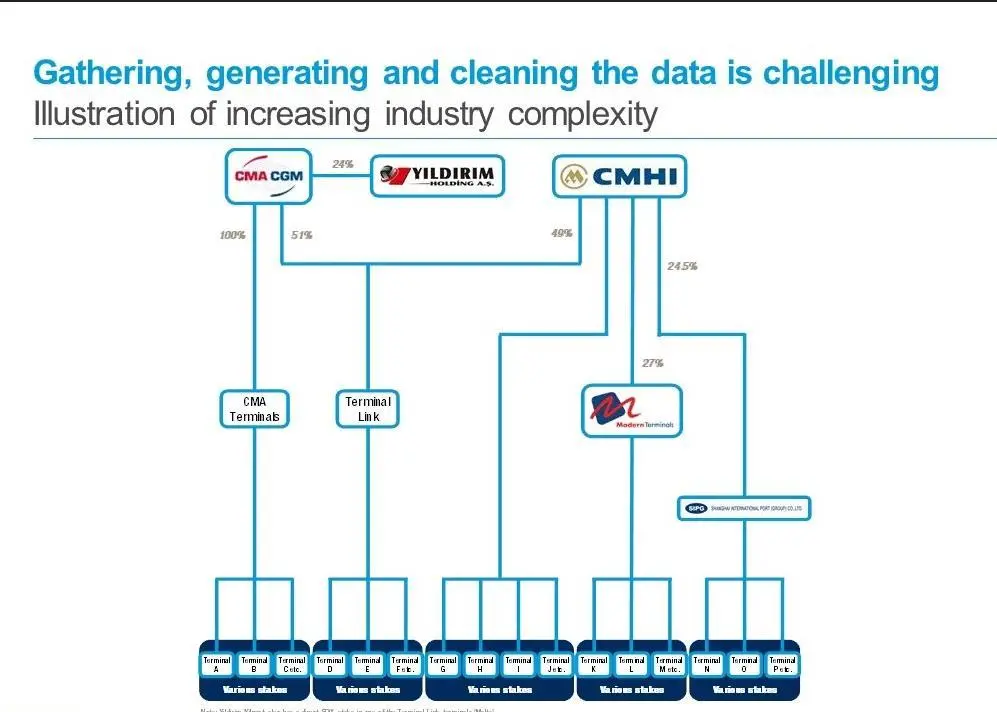
The report’s purpose is to identify, analyse and objectively ranking companies with hands on operational commercial expertise in running container terminals on an international basis.
This year’s report has seen a strong focus on M&A activity, with multiple consolidation deals including Cosco merging with China Shipping and CMA CGM acquiring APL. As well as strategic alliances – such as Hutchinson selling its stake in Euromax terminal to Cosco.
During a webinar on 18 October, Neil Davidson, senior analyst of ports and terminals at Drewry, explained: “The problem for the industry right now is that there is trouble for people to negotiate any type of new deal because the new M&A#s are still being developed.”
“No-one knows the certainty of the new alliances, which all become a reality in 2017, so there is a blurred boundary as to what product services each will have once they are fully in place. The industry is uncertain.”
He added: “It is hard for anyone to nail down and sign on the dotted line, this is both difficult in the short term and the long term to make decisions about new terminals and raising capacity.”
Another key theme was that Global Terminal Operators (GTO) and International Terminal Operators (ITO) have both taken their foot of the gas when it comes to greenfield projects.
Drewry said this could be because GTOs/ITOs are facing the ‘perfect storm’ of challenges and pressures in margins.
There is a softening of demand growth, alongside higher opex and capex costs due to bigger ships. As well as this there is increased business risk from larger liner alliances and carriers pressuring for lower prices.
The report released the throughput league tables for both total teu measure and equity teu measure.
Hutchison Ports with 1.1% growth and 81.0m teu sat at the top of the table for total teu measure, in front of APM Terminals (69.3m teu), PSA International, Cosco Group and DP World.
While PSA International topped the equity teu measure table with 53.1m teu, Hutchinson followed with 47m teu then DP World, APM Terminal and China Merchants Port Hds.
Mr Davidson agreed that in the future there could be a danger, given the slowdown in port development, of a lack of port capacity.
He explained: “Operators are being cautious, demand can be dynamic and change quickly but development is harder to change. Therefore, if there was a sudden change it could possibility cause an issue.”
“If terminal operators are pushed too far with prices they may say they will not invest and there could be a lack of capacity in the future in key locations.”
The report highlighted that all capacity expansions plans could be under review by operators as there is a great deal of caution being taken, especially for greenfield expansion.
It concluded that there seems to be two extremes in the industry at the moment – cautious holdings and aggressive expansions.
Mr Davidson concluded: “Alliances are still taking shape, all three become a reality in 2017, these are not stable forever – something could happen and they change again. The industry cannot rest on its laurels.”
Related Articles
 BULK HANDLING
 BULK HANDLING
 BULK HANDLING