






SHOCKWAVES, VULNERABILITIES AND PREDICTIONS FOR 2021
What lies ahead for the maritime sector in 2021? Against a background of the impact of COVID-19, Felicity Landon highlights select expert views.
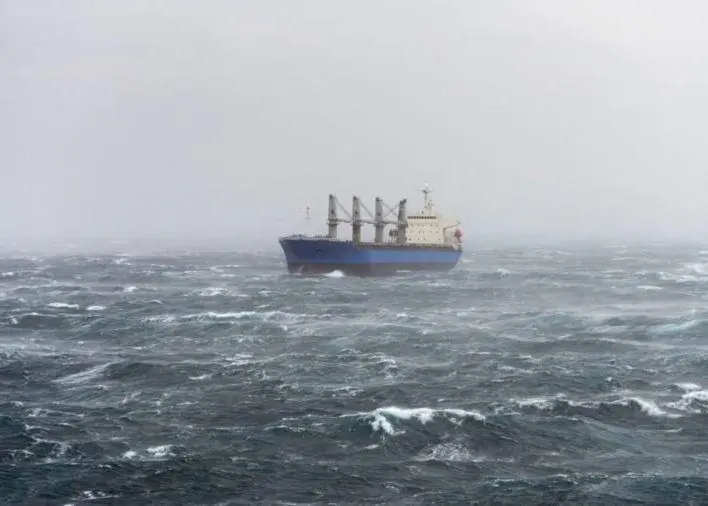
COVID-19 laid bare the vulnerabilities of the maritime sector in 2020 and highlighted challenges around connectivity, financing and the particular difficulties faced by small island developing states (SIDS), said experts at the launch of UNCTAD’s Review of Maritime Transport (RMT) 2020.
The report, published before the end of the year, predicts that global maritime trade will plunge by 4.1 per cent over the full 12 months of 2020, due to the unprecedented disruption caused by the pandemic. It warns that new waves of the pandemic, further disrupting supply chains and economies, might cause a steeper decline, and that the overall impact will also foil growth prospects.
While no one will be surprised to hear of the ‘shockwaves’ sent through supply chains, shipping networks and ports during 2020, we can all be forgiven for hoping for better times ahead. However, UNCTAD describes the short-term outlook for maritime trade as “grim.”
If the pandemic is brought under control, it expects a return of maritime trade growth, with expansion of 4.8 per cent in 2021. However, it urges the maritime transport industry to brace for change and be well prepared for a transformed post-COVID-19 world.
“The global shipping industry will be at the forefront of efforts towards a sustainable recovery, as a vital enabler of smooth functioning of international supply chains,” says Mukhisa Kituyi, Secretary-General, UNCTAD. “The industry needs to continue mitigating the impact of inward-looking trade policies and protectionism.”
As the RMT emphasises, predicting the pandemic’s longer-term impact, as well as the timing and scale of the industry’s recovery, is fraught with uncertainty.
SEA-INTEL – “UNCHARTED TERRITORY”
Alan Murphy, CEO, Sea-Intelligence, told Port Strategy: “I would be comfortable talking about a forecast in any year other than 2021. But any model based on the past is invalidated and we are in completely uncharted territory.”
A year ago, who could have predicted the turbulence of the container sector, with rocketing freight rates, container shortages, port congestion and the tangle of service disruptions and diversions?
Faced with Asia-Europe container freight rates that in some cases have risen from around £1,000 to £12,000 in a matter of months, some UK shippers have made the tough decision to halt shipments because the high rates are making low-cost goods unviable.
“It is only worth paying that rate if you have a container full of iPhones – not a container full of plastic toys or household goods,” one shipper told Port Strategy.
Murphy says: “We are seeing the wildest time in 60 years of container shipping right now.” As he explains, the shortage of containers is at the root of the issue – or, rather, that empty containers are in the wrong places, due to the extraordinary ups and downs in supply and demand through 2020. Chinese New Year 2020 and then China’s COVID-19 lockdown and factory closures, was followed by the precipitous fall in demand across North America and Europe, and then a dramatic peak in demand that started in July “and is still ongoing in January”, Murphy adds.
As lines blanked East-West sailings in response to lower demand, so the empties that would have been returned on those services began to pile up in depots. “Some areas have seen a fast recovery [in demand] and others slower, but containers have seen an absolutely unprecedented recovery and then a boom on top of that,” says Murphy.
There has been particularly massive growth on the North America transpacific trades, with container volumes up by 20-30 per cent for the past few months which, he says, is not sustainable and part of a “sham recovery”.
“Much of what was moved in the second half 2020 was lockdown focused – a lot of PPE, home office equipment and furniture, fabric to make homemade clothes, building materials. Consumption has moved from services into longterm durables. But whenever we see a lifting of [COVID-19] restrictions, we will see a sharp shift to services.”
He is reluctant to put a date on that. Many retailers have been restocking and building inventories they say they need to meet massive demand, but there is a danger of everyone in the supply chain building up inventories by 10 per cent more than the actual demand.
“At some point in 2021, this will come to a screeching halt. Carriers are aware that this will happen. Some are accusing shipping lines of taking advantage. Of course they are. If you are in a market where demand outstrips supply, prices will increase very fast and that is what we are experiencing at the moment.”
While most cargo moves on contract and will not be directly affected by the surging spot rate, when shippers have used up their contracted volumes and still need more, they will find themselves paying a considerably higher price.
We are, says Murphy, seeing a reversal of the long-accepted situation where ocean freight has been such a tiny part of the overall cost of goods that rate increases have minimal impact on the final price. “We are now reaching the level where people have cargo of US$25,000 value and are asking – am I really going to pay $8,000 to move it? It is absolutely pandemonium.”
Meanwhile, ports are struggling to handle the volumes and can’t move the containers fast enough; containers are piling up in terminals so vessels can’t get in to unload and stay anchored outside major ports, waiting for days to get a berth.
Some expect this extraordinary demand to continue long enough to run into the start of the normal annual peak in June/July. That seems optimistic, says Murphy – “but then again, the current high demand has lasted far longer than anyone would have expected”.
IHS MARKIT – THE CLIMB BACK
Global recovery in trade is expected in 2021, with particularly strong growth in the second quarter, IHS Markit predicts in its monthly global trade monitor for January 2021.
“Taking into account the first three quarters of 2020, all top economies suffered a decline in exports year-on-year ranging from -0.9 per cent for China up to -21.5 per cent for Russia. This translates to a fall of -10.4 per cent year-on-year for the whole top ten group,” says Tomasz Brodzicki, report author.
“For imports, all top economies suffered a decline, ranging from -2.6 per cent for China up to -29.7 per cent for India. The overall contraction in imports for the top ten group is equal to -10.9 per cent,” he outlines.
However, available monthly data for the fourth quarter 2020 has brought optimism. “Overall, trends observed in the real value of exports by the top ten economies point to a gradual improvement of the situation in Q3 and Q4 of 2020 (in particular in Asia). Sharper recovery is predicted for Q1/Q2 of 2021 only.”
Following an estimated 13.5 per cent drop (in value) of global trade in 2020, IHS is predicting a year-on-year increase in the real value of global trade by 7.6 per cent in 2021 and 5.2 per cent in 2022.
UNCTAD
UNCTAD’s RMT highlights the plight of small island developing states (SIDS), being among the most affected by climate change and the least connected. Chad Blackman, Barbados ambassador to the UN and chair of the WTO committee on trade and environment, notes: “During the pandemic we have seen even more the high reliance of SIDS on imports which are critical for food security, pharmaceutical drugs imports and medical equipment, while also relying on effective maritime transport for exporting goods.”
Significant disruption to supply chains, particularly for small and medium enterprises, has driven up the costs of both importing and exporting – and the projected 4.1 per cent decline in maritime trade would cause a “massive impact” on the ability for some member states to provide goods for their populations at reasonable cost, he adds.
The added effects of climate change mean that smaller independent states and countries across the world face an even greater prospect of negative growth, he says. For example, most Caribbean states have experienced at least one Category 4 or 5 hurricane in the past four years, and in a situation like this when most of their food is imported from Miami, “there is a pause or stop in transport of critical food to our economies as a result”.
Stepping up resilience is key but finance is a major challenge. “Many SIDS are precluded from the necessary concessions on global finance to be able to retrofit ports to adjust to these global shocks.”
Port facilities need to be upgraded, he says, and he called for a “very real conversation” with international financial institutions that will allow countries to build their capacity. Without a financial mechanism to allow the sector as a whole to invest in port capacity to absorb international shocks, spreading repayment over time, the cost of shipping will increase astronomically, warns Blackman.
Related Articles
 BULK HANDLING
 BULK HANDLING
 BULK HANDLING