Getting it right
The TT Club explains how the right policy can lead to greater operational efficiency – and better terms from your insurer.
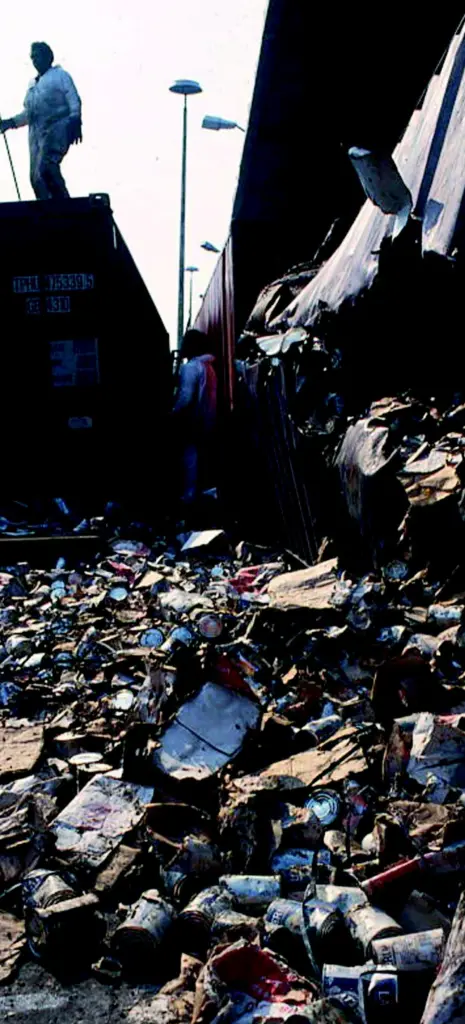
Buying insurance is often regarded as one of those tedious chores “someone in Finance” has to go through each year, but in today’s world it is something that should get the attention of senior management. Buy the wrong policy, and a serious accident could turn into a major financial disaster, as your friendly insurer points to the relevant section of the agreed conditions and reminds you that the loss suffered is not covered within the terms of the policy.
On the other hand, buying the right policy with welldrafted conditions from someone who understands your business can drive operational efficiency within your company. In turn this leads to better claims statistics and more favourable terms from your insurer.
As with all insurance, the key is to use a broker who is in tune with your business and its particular requirements. The man in the High Street may be a walking encyclopaedia when it comes to insuring your house or your car, and he undoubtedly knows the life assurance market inside-out, but what use is that to you if he can’t tell a bobcat from a gantry crane, and doesn’t know the difference between a twist-lock and a TEU?
When you are seeking to find the right home to insure several million dollars-worth of plant and equipment, and buy similar amounts of liability cover, it makes sense to seek out the specialist brokers who, in turn, will know where the specialist insurers are to be found.
Choose both the broker and insurer with the same care as you would any other supplier – but get them to come down among the hardware and see the operations at close hand. See how they react to the sight of a massive gantry crane and assess the questions they ask: are they naively impressed by the sight, or making a shrewd professional assessment?
Ask yourself some “what if” questions: give yourself some nightmares, imagine the worst catastrophe that you can, and then add another 50%. How would your business survive? What sort of help could you expect from your insurers? In recent years there have been several failures in the response to disasters, which investigations have attributed to collective failures of imagination at the highest levels. Do not let your organisation also fall victim to any such corporate myopia.
CONSIDER THE DEDUCTIBLE You should consider carefully what level of deductible or excess your company is willing to carry: in general the higher the figure you will accept, the lower the premium. Set the figure too low, and you will merely be trading dollars with your insurer; set it too high, and a run of bad accidents can seriously deplete your financial reserves. The right level of deductible can also be a force for good, by using it internally to drive up standards. It certainly concentrates managers’ minds that, if an accident happens on their patch, they will have to bear the cost of the deductible against their cost centre’s bottom line.
The insurer’s policy should be as comprehensive as possible. After all, your operation is large and complex, and the risks are numerous. You may focus on what you perceive to be the main risks to your business but just because you haven’t thought about a risk, or have never come across that type of accident, doesn’t mean that it will never happen. A good broker will not only know his way around the market, but will also know what questions to ask to establish exactly your needs, and should in so doing point out these possibly overlooked risks.
Even the best “comprehensive” policy probably does not cover all the risks of your business: most countries have regulations reserving some classes of insurance – for instance, motor vehicle third-party risk or employer’s liability – to specific, or specifically-authorised, insurers. You need to make sure that there are no horrible gaps between the different covers: as one of our more cynical colleagues liked to say: “If there is a gap between policies, it is only a matter of time before someone falls into it”. Conversely, you need to make sure that any overlapping of covers is reduced to a minimum and that you have a clear understanding as to which insurer will deal with a claim. If you wait until after an accident has happened, you can consume inordinate amounts of expensive management time trying to sort out the problem.
Good insurers are not just there at renewal time or when claims happen but should be taking an interest in your operation throughout the year. After all, they have an interest in ensuring that your business is healthy, and both sides will want to build a long-term relationship. However wide your experience, there may well be circumstances that you have never come across before, but a good specialist insurer, with experience of dealing with operations like yours in many different countries, may well have seen something similar.
Insurance is never a substitute for good management, but good managers use their insurance intelligently to help in their eternal quest to drive standards up and costs down.
Related Articles
 CONCESSIONS & INVESTMENTS
 PORT & TERMINAL NEWS
 INSIGHT & OPINION