

Demand holds strong
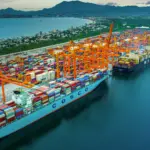
Ports and terminal operators are continuing to invest heavily in additional ship-to-shore container gantry cranes, in order to keep pace with the sizeable annual growth in box traffic volumes. Rowland Armstrong reports.
Atotal of 275 new cranes were commissioned during 2005 (see Table 1), which added around 8% to the 3,400 already in service at the start of that year. This increase contrasted with a very limited disposal of older cranes. By late in 2005, a further 280 were confirmed on order for delivery throughout 2006 (and into 2007), thereby adding a further 7.5% to the world’s overall count of dedicated quayside container cranes.
These annual increases may seem impressive but are only just meeting the ongoing rise in demand. Quayside and in-terminal capacity remains tight at many seaports, even though less congestion was experienced worldwide during 2005 than in 2004. However, the crane fleet is increasing more rapidly in capacity terms, because the majority of orders are now for larger post-Panamax units. These are required to handle the growing numbers of out-sized containerships, most of which have a width of at least 20 container rows. Many of the very largest vessels, of 7,000-8,000TEU capacity and above, are of 22-row width or greater. A crane outreach of 56m, from the seaward rail, is usually a minimum requirement for working across 20 container rows, whereas up to 62m is needed for 22 rows. However, crane dimensions have already been extended much further, to accommodate vessel widths of 24 or even 25 container rows.
Upwards of 60% of all cranes supplied in 2005 were 56m outreach or greater, and over 40% were 62m and above. These percentages will be even higher in 2006, when cranes of 62m outreach or greater are certain to account for at least half of all deliveries. Moreover, as much as a third of global production will then likely be of an ‘extra-large’ 65m outreach or more. Cranes of this monster size are still relatively few and far between, as only 88 were operational at end-2004 (making up just 2.5% of the global count). Their number increased by 75 during 2005 and will rise by at least another 87 in 2006, according to the current order book.
Virtually all of the very largest cranes, exceeding 65m outreach, have been built in the past three to four years, with the biggest to date measuring a record 70m. These are potentially able to span a ship width of 25 container rows. Eight were delivered to ports in China (Qingdao and Chiwan) during 2005 and, although no more are currently on order, cranes of 68m outreach are under construction for ports in the Mid-East. Six are going to Jebel Ali where they will add to 18 (also of 68m outreach) installed during the past two years, and four to Mina Raysut (Salalah Port Services).
Cranes of between 65m and 67m outreach are destined this year for Rotterdam (ECT Maersk Delta and ECT Delta Division), CMA-CGM at Malta Freeport, APM Terminals at Zeebrugge and Los Angeles (Pier 400), Busan Newport Corp, Hong Kong (CT9 development), Manzanillo International Terminal (MIT) in Panama, and to Dalian and Yantian in China.
These contracts are mostly for multiple batches and some have options for further purchases attached. The current ECT/Rotterdam business covers 11 cranes, while 12 are destined for the ongoing Busan Newport project (adding to six already in place) and over 20 for Yantian International Container Terminals. APM Terminals is to take delivery of 13 cranes in total, Hong Kong six and Malta five. Three are destined each for MIT and Dalian. A further dozen (of 67m outreach) were delivered earlier in 2005 to the PSA in Singapore, while 16 cranes of 65m outreach also went in 2005 to the new Shanghai Yangshan Deepwater Terminal.
Cranes of between 60m and 64m outreach are similarly destined for a broad range of port operators in 2006, although order sizes vary more markedly. The biggest deliveries are currently being made to Euromax Terminal in Rotterdam, MSC Terminal at Valencia and again to the CT9 development at Hong Kong, with these new sites collectively taking 25 cranes (of 60-64m size) during 2006. Other recipients will be Bremerhaven (NTB), Felixstowe, Le Havre, Hamburg/Altenwerder, Gioia Tauro, Seattle, Gothenburg, Port Said, Beirut, Bandar Abbas, Khorfakkan, Busan/Kwangyang (South Korea), and Fuzhou, Ningbo and Nansha (in China). This entire group will receive over 55 cranes throughout 2006.
SMALLER PANAMAX IN LONG-TERM DECLINE In contrast, the demand for smaller Panamax cranes remains in longterm decline, despite their continued numerical dominance and crucial role played at many feeder and smaller, less-developed ports around the world. The definition of Panamax size is less than 44m outreach, which is the approximate cut-off point below which vessels of standard 16-row ‘Panamax’ beam cannot be handled. The Panamax crane still accounts for just over 50% of the world’s in-service fleet, but just 15% of deliveries made in 2005 and below 10% of those planned for 2006.
A limited number are being acquired for replacement, with the majority going to smaller terminals to handle feeder, coastal or regional traffic. Many are destined for outlying sites within Europe, while the average contract size is much smaller than that generally being placed for the largest post-Panamax cranes. A total of 11 Panamax cranes are due for delivery to ports across Europe during 2006, including Gdynia, Grangemouth, Koper, Kotka, Naples, Tallinn and the new Euromax and Kramer Terminals in Rotterdam. Other units are going to Balboa (Panama), Guadeloupe, Inchon (Korea), Subic Bay (Philippines) and Wellington (New Zealand).
Europe remains a key demand area for all sizes of crane (Table 2).
An additional 67 were installed during 2005, equating to almost 25% of global output, and over 80 are due to arrive in 2006. As highlighted, deliveries are being made to large and small terminals alike, and over 60% in 2006 will be ‘super’ post-Panamax (56m or greater). However, China has been even more active, as ports there accounted for a record purchase of 89 ship-to-shore cranes in 2005 (over 30% of world production) and already have 53 booked for 2006. Chinese ports are also intent on buying very big cranes, as many strive to attract mainline traffic in a market that is both expanding very rapidly, but also increasingly competitive. Over 90% of all deliveries currently being made to terminals in China feature cranes of minimum 62m outreach.
Chinese deliveries in 2006 will again likely outrun those made throughout the rest of Northeast Asia and Southeast Asia combined.
The latter two regions took delivery of 45 cranes between them in 2005 and have current orders pending for just over 50. The majority of deliveries in 2005 went to Southeast Asia, whereas Northeast Asia (and particularly Korea) will dominate this year. In contrast to China, ports elsewhere in Asia are taking a more varied mix of crane sizes, including much of the world’s output of smaller post-Panamax units.
Most remaining crane production is going either to North America or the region encompassing the Mid-East, Africa and Indian SubContinent, with these two regions receiving 25 and 38 cranes respectively, during 2006. Again though, the majority are of larger post-Panamax size. The balance of 32 cranes is to be supplied to ports within Central/South America and Australasia, although both these regions have purchased significantly more cranes in 2006 than in 2005. However, they are still opting for smaller post-Panamax sizes, between 45m and 55m outreach.
HUGELY COMPETITIVE Despite maintaining a substantial level of output, the world’s crane manufacturing industry remains hugely competitive and, until very recently, was largely price driven. However, as higher steel and component costs have fed through, so contract prices been forced up throughout the past year and are now greater than at any time since the mid-1990s.
In consequence, it is no longer possible to purchase a large ‘stateof-the-art’ post-Panamax crane for less than US$6m, as had been the case for many years. This price was previously sufficient to secure a high specification crane, typically featuring 56m outreach or greater, up to 40m lift-height, trolley speed exceeding 4m/second, laden hoist greater than 1.5m/second, and lift capacity (under twin-lift spreader) of up to 80 tonnes. Now, the same unit is reportedly costing up to 30% more, at around US$8m.
The prospect of higher prices helps explain the slight slowdown in ship-to-shore crane orders placed since late 2005, although most crane builders are still claiming busy production lines. Shanghai Zhenhua Port Machinery Co (ZPMC) is now firmly entrenched as the world’s leading supplier of ship-to-shore container cranes, having met over 50% of world demand in 2005. It then supplied over 150 cranes, half of which went to ports in its booming home market.
The Chinese firm is on course to build more than 65% during 2006, having the longest production backlog of any manufacturer and an enviable global order book. Its main rivals are Kalmar Industries, Fantuzzi-Reggiane Group, Mitsubishi Heavy Industries, Liebherr Container Crane, Konecranes VLC, and Paceco and its licensees (headed by Mitsui Shipbuilding and Engineering), although these are no longer achieving an output as high as ZPMC between them.
Related Articles
 OPERATIONS
 OPERATIONS
 PORT & TERMINAL NEWS