






In pole position
Polish ports are on the up, driving Baltic container volume overall. Conversely, the role of German ports in serving the Baltic is reducing, not least today due to the Russian situation. A J Keyes reports
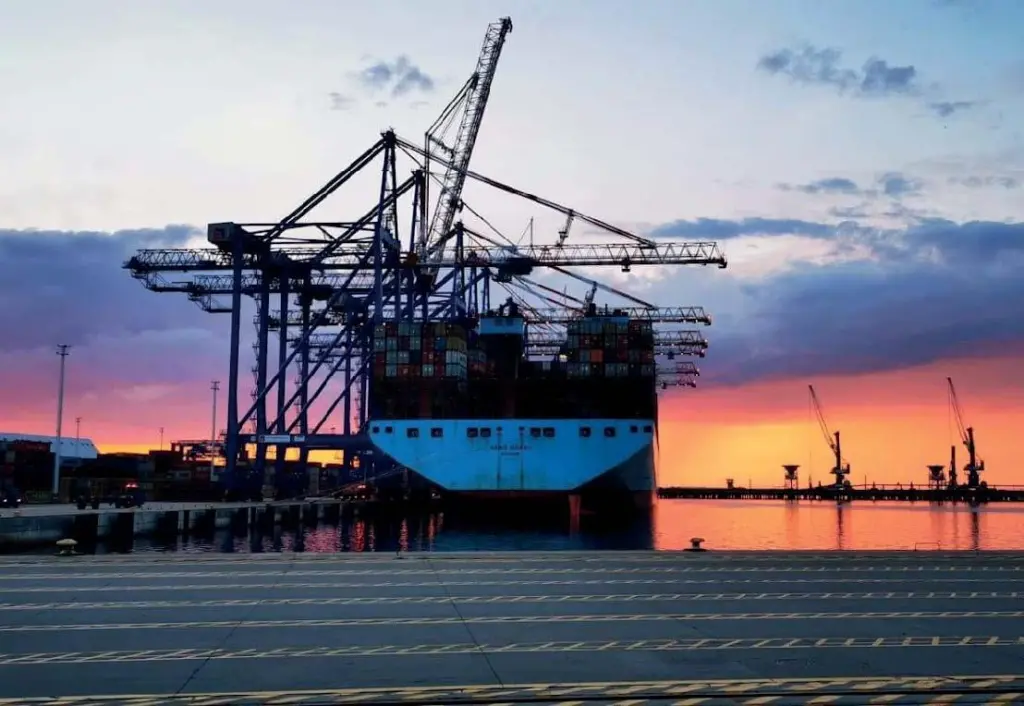
Ports in Poland have traditionally been driven by a combination of strong Polish demand (which includes Hamburg transit activity) and transshipment into the wider Baltic region. While the former remains strong, the latter has severely collapsed due to a loss of Russian cargoes direct to St Petersburg and transit into Russia via Baltic States and Finnish ports.
So, until the Russian situation stabilises or recovers, the Polish economy will remain the principal driver. This is no bad thing, with the country generating a high level of GDP growth over the last 10 years, especially the 4.6 per cent per annum between 2015 and 2019. Although the COVID-19 pandemic saw a drop of two per cent, there was a swift rebound of 6.8 per cent in 2021 and an average of 3.1 per cent then forecast by the IMF to 2028.
This positive activity supports container port growth and has been seen across the wider Baltic region. As Table 1 shows, the 2014 regional total of 7.7m TEU increased to 8.1m TEU in 2022 after having peaked at 8.9m TEU in 2019 due at first to supply chain issues as a result of the pandemic and then as Russian demand collapsed in 2022.
POLAND: THE DRIVER
Yet it is Poland’s ports which remain the driver of this regional development. For example, Gdansk has seen an annual increase between 2014-2022, with its total volumes increased from 1.2m TEU to almost 2.1m TEU over the same period.
Continued investment at Gdansk in deep water, larger cranes and longer berthing has attracted deep sea calls from Asia to serve both local Polish import-export markets and as a transshipment hub. Maersk Line remains the major liner customer of the port although the Ocean Alliance also calls now.
This level of growth can be compared to other ports in the region, also shown in Table 1, with no other individual port able to match this level of continued growth. The only exception is Klaipeda in Lithuania, although its 11.1 per cent annual rise averaged over the period between 2014 and 2022 is largely impacted by the very strong results in 2022 due to volumes from Mediterranean Shipping Co (MSC).
The weakness in the Russian economy coupled with the Russian trade embargo has resulted in a fall in total container throughput at St Petersburg/Ust Luga, which dropped substantially from over 2.2 million TEU in 2019 to 0.9 million TEU in 2022. Indeed, volumes since 2015 for the Russian ports had been growing, rising from 1.7 million TEU, which endorses the strong traditional market that has existed for goods moving to Russia. However, these days are not expected to return until the Ukraine conflict is over and trade with the country returns – which is an unknown length of time.
It is apparent that Hamburg – and to a lesser extent other North Continent ports – have also seen a sharp drop in containers feedered to/from the region, with this further underlining the scale of Russian-led disruption. As already noted, the trade sanctions impacting Russia are not expected to end at any time soon, which means that ports like Hamburg that have traditionally served Russia will not see volumes returning and alternate markets will need to be targeted to make up for any loss of container traffic.
Table 1: Total Port Volumes in Baltic Port Region 2014-2022, in ‘000 TEU
| Port | 2014 | 2015 | 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | CAGR |
|---|---|---|---|---|---|---|---|---|---|---|
|
Gdansk (Poland) |
1,212 |
1,091 |
1,299 |
1,581 |
1,949 |
2,073 |
1,924 |
2,118 |
2,072 |
6.9% |
|
Gdynia (Poland) |
849 |
685 |
642 |
711 |
804 |
897 |
905 |
986 |
914 |
0.9% |
|
Szczecin-Świnoujście Inner Terminal(Poland) |
78 |
88 |
91 |
93 |
81 |
76 |
87 |
82 |
75 |
-0.5% |
|
St Petersburg & Ust Luga (Russia) |
2,375 |
1,715 |
1,745 |
1,921 |
2,131 |
2,222 |
2,100 |
1,994 |
919 |
-11.2% |
|
Gothenburg (Sweden) |
829 |
810 |
795 |
639 |
750 |
772 |
776 |
828 |
885 |
0.8% |
|
Helsinki (Finland) |
401 |
432 |
450 |
491 |
510 |
534 |
509 |
467 |
492 |
2.6% |
|
HaminaKotka (Finland) |
575 |
555 |
631 |
690 |
653 |
678 |
621 |
594 |
629 |
1.1% |
|
Kaliningrad (Russia) |
325 |
179 |
189 |
239 |
276 |
324 |
281 |
437 |
397 |
2.5% |
|
Tallin (Estonia) |
260 |
208 |
202 |
215 |
223 |
223 |
213 |
227 |
251 |
-0.4% |
|
Riga (Latvia) |
388 |
355 |
385 |
445 |
469 |
467 |
453 |
416 |
461 |
2.2% |
|
Klaipeda (Lithuania) |
450 |
392 |
443 |
472 |
750 |
703 |
640 |
667 |
1,047 |
11.1% |
|
Regional total |
7,742 |
6,510 |
6,872 |
7,497 |
8,596 |
8,969 |
8,509 |
8,816 |
8,142 |
0.6% |
|
-15.9% |
5.6% |
9.1% |
14.7% |
4.3% |
-5.1% |
3.6% |
-7.6% |
Source: dataand.com
So, while ports in Poland, notably DCT Gdansk, continue to increase in throughput importance, container volumes at ports in Germany, especially Hamburg, continue to struggle. In 2014, total port throughput was almost 15.6 million TEU, but at the end of 2022 it had fallen to just under 13.5 million TEU, a decrease of just under 1.8 per cent per annum, impacted by a lack of demand for transhipping to Russia.
HAMBURG DECREASE
Hamburg has seen a decrease in total volumes for 2022, dropping from 8.7 million in 2021. Since 2014, the port’s average decline has been 2.0 per cent per annum. A series of workforce strikes and congestion during 2022 must also be regarded as influencing factors negatively influencing the port’s throughput decline.
Wilhelmshaven volumes have fluctuated in recent years, linked primarily to Maersk Line’s use of the facility. Despite a very strong post COVID-19 rebound in 2021, the port continues to struggle to retain volume growth and regular services calling.
As a result of the volume fluctuations at Hamburg and Wilhelmshaven, volumes at the major ports in Germany listed in Table 2 have decreased by an average of 1.8 per cent per annum between 2014 and 2022. Indeed, the total in 2022 of just under 13.5 million TEU represents a decline on the position in 2014 when the totalled for containers handled was almost 15.5 million TEU.
Within this assessment range, there was also a decline in 2020 of just over one million TEU, from 14.8 million TEU (2019) to 13.8 million TEU (2020), due to the COVID-19 pandemic. While there was a rebound in 2021 to 14.4 million TEU, the impact of the economic sanctions on Russia was a major factor in the decline the following year in 2022.
Table 2: Total Port Volumes at Port in Germany, 2014-2022, in ‘000 TEU
| Port | 2014 | 2015 | 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | CAGR |
|---|---|---|---|---|---|---|---|---|---|---|
|
Hamburg |
9,775 |
8,848 |
8,929 |
8,860 |
8,741 |
9,282 |
8,578 |
8,700 |
8,300 |
-2.0% |
|
Bremerhaven |
5,731 |
5,467 |
5,510 |
5,458 |
5,422 |
4,850 |
4,767 |
5,005 |
4,518 |
-2.9% |
|
Wilhelmshaven |
67 |
427 |
482 |
520 |
656 |
665 |
423 |
713 |
663 |
33.2% |
|
sub-total |
15,573 |
14,742 |
14,921 |
14,838 |
14,819 |
14,797 |
13,768 |
14,418 |
13,481 |
-1.8% |
|
-5.3% |
1.2% |
-0.6% |
-0.1% |
-0.2% |
-7.0% |
4.7% |
-6.5% |
Source: dataand.com
It is clear that while ports in Poland, notably DCT Gdansk, continue to increase their importance in the Baltic market, Hamburg and German ports are less successful and are continuing to struggle to maintain recent container throughput activity. Also, Hamburg has seen its share of overland containers to/from Poland undermined by the improved costs and efficiencies available at Polish ports, a position that looks set to continue. For Russia, sanctions and considerably lower port volumes is now the new norm.
Related Articles
 OPERATIONS
 OPERATIONS
 OPERATIONS