Africa explored
Under the control of the World Bank, a major study has recently been conducted into the African ports industry studying both sub-Saharan African and North African ports.
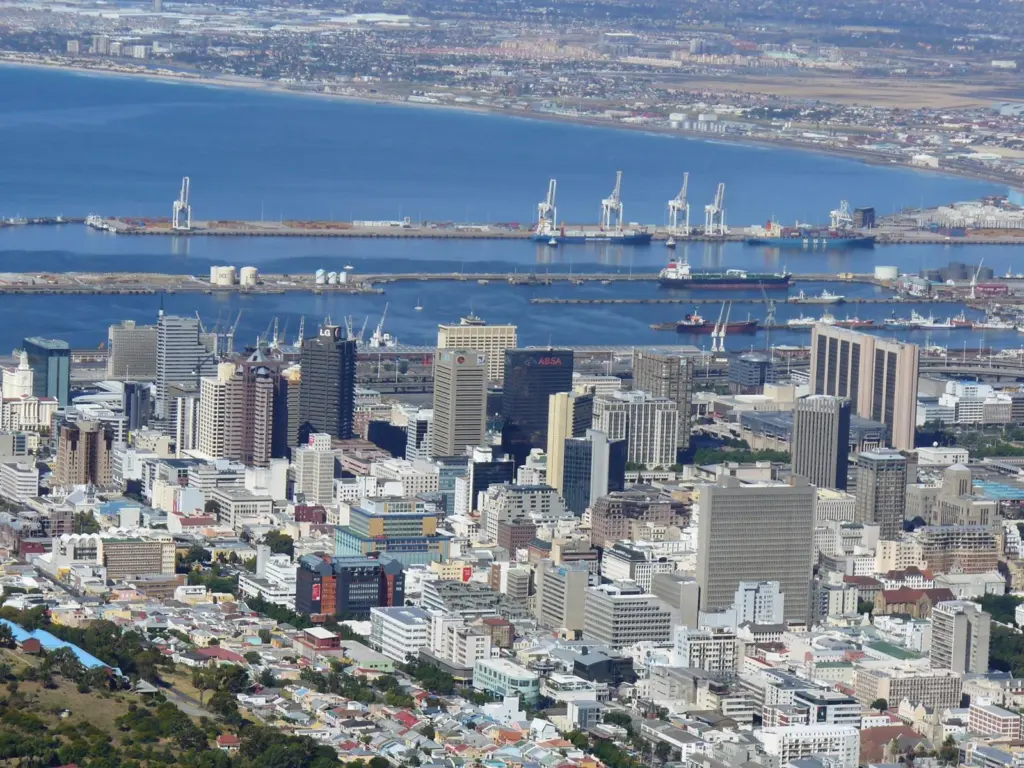
The ports study, undertaken by Ocean Shipping Consultants, is one element of a multi-part study looking at all the key elements of African infrastructure with the aim of assessing the current situation and future plans in order for all interested parties to be able to more efficiently channel future development efforts.
Looking at the Sub-Saharan Africa element of the study, the scope of the study covered 26 countries and over 80 ports; some received a comprehensive review and some a partial review. Taking the comprehensive review as an example, the main “indicators” examined for each port were port authority organisation, workforce, activity and performance, facilities and infrastructure, equipment profile, capacity profile, cost, performance, management model and competition, and private participation.
Under each of these headings diverse questions were asked and then to supplement this information a separate country review and finally a cross country analysis were undertaken.
All three regions – east, southern and west Africa – experienced an increase of over 200% in container volume 10 years on from 1995. West Africa saw the biggest increase in box traffic volume, a rise of nearly 400% to over 4m teu.
While container traffic increased, however, strong growth was also maintained in general cargo traffic growth indicating that container penetration into Sub-Saharan African general cargo trades has some way to run. Each of the three regions saw increases of over 200% and southern Africa an increase of over 500%.
In an institutional context, it is noteworthy that only two countries have comprehensively adopted the favoured landlord port model, Nigeria and Ghana. A large number still retain the old style service port model where the public sector is the manager and operator but having said this the number that have concessioned container terminal facilities runs into double figures.
There is also the hopeful sign that around 10 countries have either recently or are in the process of undertaking new national port masterplans. While not all address institutional reform but the majority do. On the downside, there is only minimal evidence of the independent regulation of ports – i.e. arms length regulation.
Meanwhile, examination of the Sub-Saharan African study ports from an infrastructure development point of view shows that each of the three regions – east, south and west – are severely short of available capacity. It has to be said, though, that subsequent to the end of the study period the capacity shortfall situation has lessened a bit, generally due to the impact of the economic downturn and in the case of South Africa in particular due to the start-up of operations in the new port of Coega.
What remains the case, however, is that there is a major shortage of transhipment capacity on both the east and west coasts of Africa.
Equally, the study confirms that, with the exception of South Africa, Sub-Saharan African ports suffer from a major lack of efficient interfacing road and rail infrastructure, and that to consider new port development without considering this aspect is very short-sighted. One barometer of the lack of proper road and rail infrastructure was the relatively low level of containerised transit traffic moved across green borders, a situation which remains largely the same today.
For more on the Africa Infrastructure Country Diagnostic, please visit the project website:
http://www.infrastructureafrica.org
Related Articles
 POST SCRIPT
 POST SCRIPT
 POST SCRIPT