

New Yorker OPINION, October 09 issue
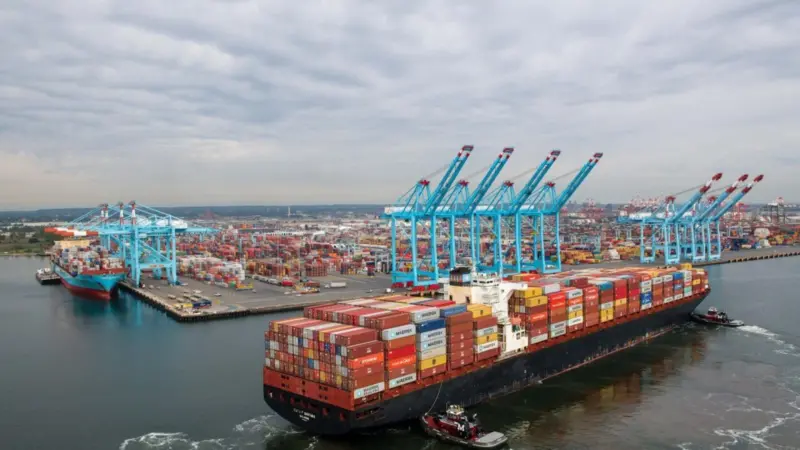
There is a fine line between great foresight and lemming-like marches, so which camp do the major container carriers fall into, as they continue to support their orders of dozens of mega-ships, booked at prices of circa $100-$130m each?
While nobody is popping champagne corks, economists have come around to the view that world trade growth will turn positive in early 2010, if not late 2009.
Admittedly fueled by support of Export Credit Agencies (ECAs) in Korea, the orders for the huge behemoth vessels have remained in place while carriers rationalise in the short term.
Maersk, the “Big Kahuna” of carriers (a New York expression) is raising stock for the first time in thirty years, and talking about its first ever public bonds. CMA CGM, number 3 in the league tables, will actually sell shorter term assets – but keep supporting its vessel orders.
To me, these carriers staying the course fall squarely in the foresight category; trade flows will rebound, and inventive logisticians will find ways to fill up all those boxes. For players in the port business, it’s worth observing the dynamics of the carriers, who are, after all, the ports’ business partners in the truest sense.
Backers of port projects, whether they be state/regional entities or local voters, all need to be reminded of the sparks now being kindled by trade economists. The folks on the Left Coast, in Los Angeles, have the right idea; recent reports have it awarding a $47m contract for expansion of the China Shipping berth (complete with electrical hookups for shore-side power).
The Los Angeles investment, a healthy amount in our industry, will bring jobs, and support increased cargo throughput. As new supply chains are being built and existing moves tweaked, the ports can be at their focal point; with the caveat that that the fulcrum of goods movements is not stationary.
It can move up or down the coast – especially when your neighbour invests, and you don’t. So, it’s vital that port planners continue to peer through the economic fog, remembering that investment payoffs in this business are not by next quarter’s teu throughput report, but rather by benefits accruing over decades.
Related Articles
 INSIGHT & OPINION
 INSIGHT & OPINION
 INSIGHT & OPINION