






Eu Ports Reform: Not A Slam Dunk
Maintaining competitiveness and a healthy inward investment picture are two strong areas of challenge evident in the recent EU Ports Reform package. There are concerns Mike Mundy reports
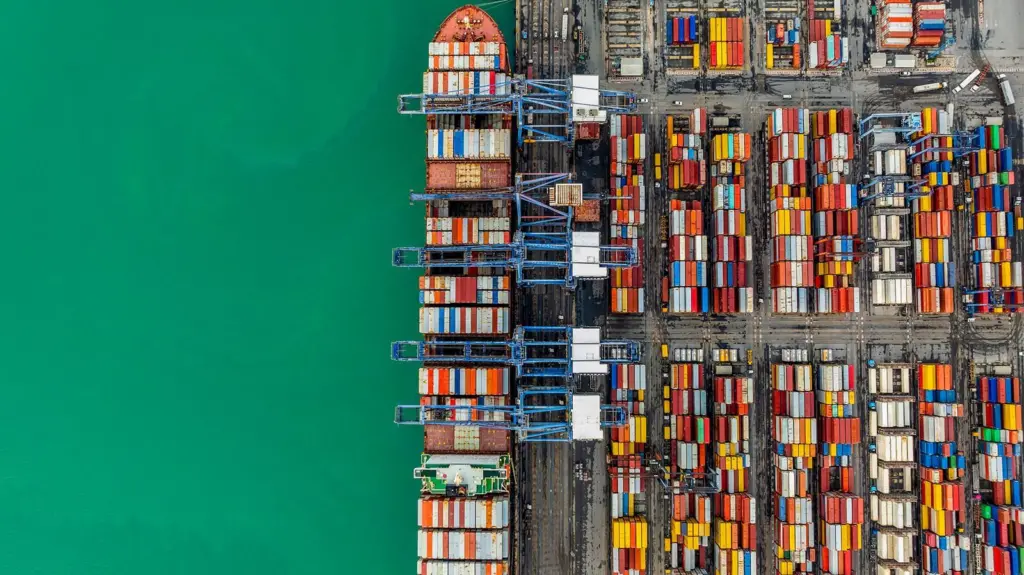
Delivering a new agenda for port reform in Europe is not a slam dunk. Introducing a reform package that is acceptable to all, or even the majority, of the 27 countries that make up the EU is by no means straightforward. History tells us this. The new port reform agenda released by the European Commission, in early March, has been the subject of consultation with various industry sector groups but it remains to be seen whether it passes muster for all concerned.
Is 49% the benchmark for future investment by U entities in the EU ports sector?
The five main action areas embodied in the reform package are those highlighted in Table 1. Together they are designed to provide what the Commission calls “… a clear framework for the future of European ports.” At the same time, it is seen that the reform package will strengthen logistics and supply chains and promote resilience across the board.
Significantly, in responding to the introduction of the reforms FEPORT – the voice of private companies and terminals in Europe – notes: “At the heart of the strategy lies the concept of resilience.” And underlines that: …”without resilient ports, logistic chains cannot effectively serve the European market.”
FEPORT also sees as a big positive the recognition in the reform package of “the intense international competition faced by European ports and the risk this poses to their competitiveness.”
FEPORT acknowledges, however, that the reform package as of today represents something of a wish list. There are obviously aspects of the reform package that the Commission can directly influence in line with the goals stated – for example, new criteria and guiding principles for EU funding, and taking a leading role in putting in place measures designed to greatly enhance cyber security. There are distinct areas within the reform package where it is clear that the Commission will be able to play a leading role in bringing about the necessary changes foreseen.
There are certain areas, however, where the market – the port industry itself – feels that there is a need for a ‘soft touch’ rather than be exposed to over-regulation.
FEPORT notes: “…we believe that competitiveness, supported by investment and smart regulation, must remain a central priority.” And elaborates:
“As ports operate in a global marketplace, regulatory and compliance costs that apply exclusively to EU companies increase the risk that cargo flows will be diverted to third country ports. Recognising this risk is important but not sufficient. Addressing this challenge requires improved access to public funding and an adaptation of the regulatory framework.”
Table 1: The New EU Ports Reform Package Features Five Main Action Areas
| Strengthen Competitiveness, Innovation and Digitalisation |
|---|
|
• To improve coherence and coordination, the Commission will develop criteria and guiding principles for EU funding and investments in third-country ports. • The Commission will also develop criteria and guidance on foreign ownership and control, focusing on ports identified as strategic dual-use infrastructure. • The Commission will support the digital and green transformation by promoting innovation, and scale-up and uptake of innovative technologies. |
|
Advance Energy Transition, Sustainability and Clean Industries |
|
• The Commission will accelerate permit-granting and provide faster assessment procedures for strategic energy and environmental port projects. • The upcoming Electrification Action Plan will support port electrification, access to the grid, and the deployment of clean energy. • The Commission will promote partnerships for energy cooperation in and around port areas for sustainable use of energy, including hydrogen. |
|
Protect and Secure Ports |
|
• The Commission will strengthen port security by updating and revising existing guidance, including on emerging threats, and promote a global level playing field for EU ports security. • To fight drug trafficking, the Commission will establish frameworks for third-country port assessments and for background checks for port workers, improving alignment of customs controls across EU ports with better global security protocols. • The Commission will establish a forum for Member States’ cybersecurity and port authorities to exchange best practices, and an EU-wide security risk assessment will identify the most pressing cybersecurity risks and mitigation measures. |
|
Access to Finance and Investments |
|
• Building on existing EU funding instruments, including the Connecting Europe Facility, Cohesion Policy funds and InvestEU, the Commission will support ports with clear and targeted funding principles aimed at improving the coordination and efficiency of EU financing. •The Commission will also facilitate access to advisory services and de-risking tools, with particular attention to the needs of small and medium-sized ports. |
|
Social Cohesion, Skills and Quality Jobs |
|
• The Strategy recognises the important role of small and medium-sized ports and outlines specific initiatives on innovation, clean energies, security and connectivity to support these ports. • The Commission will support the development of a skilled next-generation workforce across all blue economy sectors through the Blue Generational Renewal Strategy. A new Pact for Skills for the ports sector will focus on upskilling, reskilling and inclusion of workers. • The Commission will prepare guidance on the application of maritime safety legislation to port workers on board ships, as well as on safe handling of alternative fuels in ports. |
At a general level, high carbon prices are criticised for hurting European competitiveness, leading to potential “carbon leakage,” where companies move production to countries with weaker environmental regulations.
Specifically in port terms, there are concerns that ships will reroute to non-EU ports to avoid paying for emissions. EU ports in the Mediterranean and Southern Europe (for example, Italy and Greece) have raised concerns about losing transshipment business to neighbouring, non-EU ports like Tanger Med in Morocco and East Port Said in Egypt.
FEPORT, along with others, has consistently emphasised the importance of legal clarity and the stability of the regulatory framework for private investors in the port sector. By extension, the reform package must be configured so as to maintain competitiveness in the face of such challenges. Equally, this applies to the impact of geo-political tensions now particularly manifest in energy prices.
The pendulum continually swings to the need to be resilient and to maintain competitiveness.
Clearly, the thinking here is to achieve some sort of parity with countries outside the EU where, for example, there may be a strong level of public funding for basic port infrastructure and to mitigate through regulation etc the negative impact of directives such as the EU Emissions Trading System (EU ETS) which focuses on shipping transport operations. This requires shipping companies to purchase and surrender allowances for their greenhouse gas emissions, functioning as a “carbon tax” on maritime transport. The ETS covers 100% of emissions for voyages between two EU/EEA ports and 50% of emissions for voyages starting or ending outside the EU/EEA.
The bone of contention with EU ETS is multi-faceted.
INVESTMENT DILEMMAS
All parties agree that attracting private sector investment into EU ports is of fundamental importance. There is a lot on the investment agenda for ports – keeping pace with demand, the greening of port activities, combatting drug trafficking, cyber security system investment etc – and public private partnerships etc. are an important cornerstone of achieving this.
It is thus not surprising that concerns have been, and continue to be, expressed in this context right through from the role of funding to constraints on foreign direct investment (FDI) that can reduce investment, increase bureaucracy and restrict operational openness.
FDI is a bigger topic today than it has been even in the recent past. Largely, this can be attributed to Donald Trump and the concerns raised by him about the spread of Chinese influence. He identified China’s global port investments as part of a deliberate long-term strategy. Further, that with ports closely associated with supply chains, military mobility, energy imports and industrial resilience, there are significant risks when foreign actors gain influence over such assets.
The EU has approximately 30 port facilities in which Chinese has invested.
The European Commission now requires a “thorough assessment” of foreign investments in ports deemed critical for supply chains – basically a detailed screening. Prior to the release of the EU Ports Reform package there was a lot of speculation about a cap being placed on FDI-based port investments in the EU. This did not actually materialise, but it is relevant to note that also launched by the EU around the same time as the ports package was its much-awaited Industrial Accelerator Act, which proposes a new set of conditions for specific industry sectors. One of these conditions is that foreign investors do not acquire more that 49% – a figure which is seen by many as a benchmark for the ports sector going forward.
This highlights the task at hand – achieving an equitable balance between regulation/bureaucracy and fostering a competitive and investable ports sector. Further, that this task will continue to have new pressures placed upon it – market and political forces but also significant regulatory initiatives and, notably, the moves to update the EU ETS programme by mid-year and the introduction of the comprehensive, digitally led, reform of EU Customs in a programme that will extend through to 2038.
Related Articles
 OPERATIONS
 OPERATIONS
 OPERATIONS