


STS 2025 order book & trends
STS crane deliveries in 2025 reveal the high concentration of the sector and the very high dependence on Chinese manufacturers, which is not easily turned around.
By Fabian van der Poel and Johan-Paul Verschuure, Rebel Ports team
Ship-to-Shore crane deliveries are a reliable and tangible display of near future capacity shifts. Analysing crane deliveries gives another insight into the key prevailing trends in the container industry. The authors analysed a dataset of 197 STS cranes deliveries to deep-sea container ports in 2025, using public news sources and terminal operator websites. The picture is one of continuing handling capacity expansion, Chinese manufacturing dominance, and a geographic centre of gravity shifting towards markets in South and Southeast Asia.
New over replacement
The vast majority of cranes reported to be delivered are intended for expanding a terminal’s capacity. Using standard productivity benchmarks for STS cranes this means that around 35m TEU of global handling capacity was expanded by the cranes analysed in the dataset. The dataset represents roughly 2.5% of growth in installed handling capacity, relative to an estimated approximate four per cent growth in global container handling capacity last year. With part of the expanded container handling capacity coming from replacement by newer and larger cranes, as well as the use of Mobile Harbour Cranes (MHC) in smaller and multipurpose terminals, the analysed data set represents the majority of the new STS cranes.
The dataset only contains some 18 cranes intended for replacement, which is well below the expected number of cranes which should be replaced considering a lifespan of between 15-20 years. Either many of the cranes are stretched beyond this lifetime, with extensive overhauls and replacement postponed as much as possible, or replacing cranes is considered to be less newsworthy.
Southeast Asia’s crane elevation
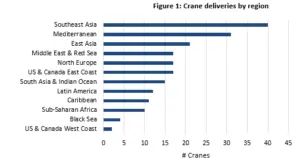
Considering the crane deliveries as a proxy of anticipated growth for the next few years, Southeast Asia remains the center of growth expectations (40 cranes). Growth is concentrated in Malaysia (13 cranes across multiple ports) and the Singapore Tuas buildout, highlighting the anticipated growth in transshipment over gateway volumes. With Durban taking care of most of the Sub-Saharan crane deliveries, the new operating entity is readying itself for realising the growth ambitions of the port.
Europe accounts for roughly 25% of the delivered cranes with 31 deliveries in the Mediterranean and only 17 in North Europe. Egypt is the standout story: the new Damietta Alliance terminal received seven HHMC cranes, while APM Terminals expanded at Port Said East, and APMT Barcelona began a five-crane expansion with three ZPMC cranes being delivered. North America adds another roughly 10% of the global crane deliveries. It is notable that the deliveries are heavily concentrated on the East Coast, and to only a very limited extent on the West Coast. New upcoming West Coast projects in the next few years may change this picture. See Figure 1.
Lifting ZPMC’S grip on the market
In recent years there have been increasing talks about cranes from Chinese manufacturers. In early 2025 headlines indicated security concerns were raised in the US about cranes from Chinese manufacturing. Also, the EU has signaled a more protectionist approach also highlighting security concerns as a key driver. This implies significant changes for sourcing quay handling equipment.
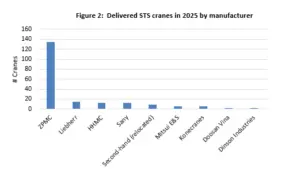
Analysing the 2025 data it clearly shows the strong grip ZPMC has on manufacturing output. Almost 70% of the cranes in our dataset were from ZPMC with the company delivering globally. When adding the market shares of HHMC and Sany the share
of Chinese manufactured cranes increases even further to above 80%. ZPMC, however, recorded an even higher market share, further indicating the pressure on the sourcing of essential container handling equipment.
The recently launched EU port strategy tries to ensure “a fair global competition for EU shipyards and equipment manufacturers,” with this holding some scope to be influenced by export financing mechanisms and other sector specific tools. Although the EU port strategy is not entirely clear on its position regarding STS cranes, a push to increase European manufactured cranes will however require much more than just funding mechanisms.
In 2025, Liebherr is a distant runner-up at 15 units (8%) and Konecranes and Kalmar jointly responsible for somewhat over 10% of the market. If all European and American cranes were required to be sourced by European manufacturers this would necessitate manufacturing capacity having to grow by up to a factor of 3 at least.
Figure 2 summarizes manufacturer output by key manufacturers.
Second-hand market
Only a very small share of 2025 crane deliveries involved second-hand cranes. Relocations included former APMT Pier 400 Los Angeles cranes finding a second life at Cai Mep in Vietnam. Also, Kalmar seem to have focused on repair and relocation recently relocating STS cranes between Eurogate terminals.
With container vessels gradually increasing in size across trades, it is interesting to witness that STS cranes are also not redeployed in line with the vessel upscaling. Where crane configuration permits, terminals could consider buying larger equipment, dealing with the higher and further lifting requirements of the larger vessels, and ‘cascading’ the older equipment down to other terminals.
Naturally the high transportation costs and risks involved with transporting cranes between terminals and commissioning/decommissioning costs play a role in this, but for new terminals or riskier expansions this option could be further explored by way of optimising the asset base and reducing investment risk.
It would help if new cranes could be designed to be more flexible and transportable for this purpose.
APMT in the lead
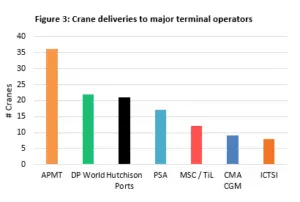
APM Terminals leads with 36 cranes across its wholly-owned and joint-venture terminals[1], reflecting APMTs strong recent extension of its terminal portfolio. DP World follows at 22, with most of its cranes being delivered along the China-EU corridor. Hutchison Ports and PSA International each received 19, with PSA’s intake concentrated at Tuas and Nhava Sheva. TiL received 12 cranes, including the expansions in Le Havre.
As such the crane delivery market is as concentrated as the shipping industry itself. If European policies are directed at increasing the share of European or American manufactured STS cranes, the headquarters of these international operators will need to be convinced. Given these operators are often non-European, strict policies and guidance will likely be needed to achieve the protectionist objectives listed in the EU Port Strategy.
[1] If cranes are delivered to a terminal shared by multiple operators, each operator will be attributed the total number of cranes delivered in this data cross-section.
Recent protectionist and security ambitions around STS cranes will be very challenging to achieve for Europe and America. Currently the market share of non-Chinese manufacturers is well below the share in demand from European and American terminals. Especially when adding the higher replacement numbers from the older European terminals. Turning this around will not be done by just creating financing mechanisms or general ‘sector specific initiatives.’ It will require a very extensive programme designed to boost capacity in the crane and equipment manufacturing industry across Europe. These type of industry policies have typically proved especially difficult to roll-out when only a few countries in the EU benefit.
Related Articles
 EQUIPMENT
 EQUIPMENT