




The shipping industry CMA reboot
This spring’s Connecticut Maritime Association conference, one of the mainstays of the New York event circuit, suffered from having too many good speeches/sessions happening simultaneously – a happy problem, I guess, for the organisers.
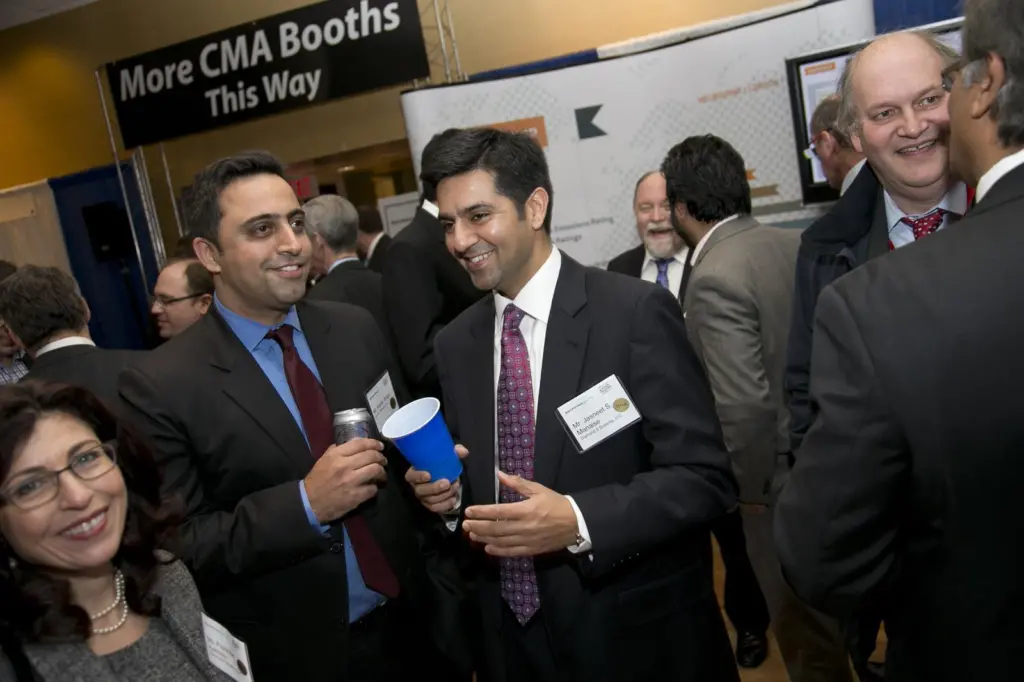
The title of the conference, Shipping 2.0, evokes ideas of renewal and reboots – one of several intertwined themes.
The panels dealing with cargo movements and freight rates are always interesting. This year, the forecasters stayed home (or maybe they were not invited back in view of their dismal track record); what we heard about, instead, was the changing nature of trade flows.
Much of the conversation concerned energy flows, admittedly a business for specialised ports and facilities. But the seismic shifts in cargo origins and destinations, in a period of only three or four years, provides some important lessons here for everyone in the business.
Certain parts of the oil tanker trade have been completely obliterated (there’s really no other word), as other modes – pipelines and trucks – bring oil to refineries. Some processing facilities had closed in recent years, only to re-open as the trade landscape enabled them to repurpose and create demand for other tankers, in routes that were previously languishing, at the same time.
What I’m describing, as I try to assimilate the wisdom from the front of the room, is clearly a planner’s nightmare. Yet this is our new economic reality.
Container trades, of more interest to many of the ports, did come up in some conversations around the conference venue with outsourcing, and then ‘in-sourcing’, supply chains are no longer immutable – and subject only to yearly tweaks.
For shipment planners, ‘optionality’ (a finance word now moving into the transport lexicon) is a key consideration. For the port community, on the business end of all these new trends, all the collective rebooting may presage an environment where last year’s flows may not necessary provide the baseline for predicting the next year’s movements.
The trends also imply that a different type of outreach is required, when dealing with big customers, who may be struggling with their own supply chains. Nevertheless, efforts expended to understand possible shifts in customers’ freight programs is time very well spent.
Related Articles
 INSIGHT & OPINION
 INSIGHT & OPINION
 INSIGHT & OPINION